Key Points
- Last week’s Fed hike, its first since 2023, is now behind markets, with attention shifting to a lighter but still significant calendar this week, headlined by Wednesday’s Swiss National Bank decision and Thursday’s Australian employment report.
- WTI crude oil sits at 93.76, pulling back from a high near 103 after a strong uptrend from a low near 72 in early August. Brent crude cooling from recent highs, even as $100 oil keeps bond markets on edge, has kept price consolidating below the broken support turned resistance zone.
- USD/CHF sits at 0.8231, pulling back after a sharp break higher to 0.8260 last week. With the SNB holding its policy rate at 0.00% on Wednesday and widely expected to stay there, the tone of the statement is the real swing factor for the pair this week.
Last Week in Review
Last week’s headline event was the Fed’s rate decision, its first hike since 2023, which landed largely as priced and removed the single biggest source of uncertainty markets had been carrying into the month. With that decision now behind markets, coverage has already moved on to what comes next, with some desks, including BofA, keeping their call for further Fed hikes in October and December as spending continues to run hot. That backdrop of a still-hiking Fed has kept the dollar broadly supported and added to the pressure on commodities priced in dollars.
This week’s calendar is lighter by comparison but still carries real risk. The Swiss National Bank’s decision on Wednesday is the standout event, alongside Thursday’s Australian employment report and a run of flash PMIs out of the Eurozone and UK on Tuesday. Central bank speakers are also thick on the ground, with the RBA’s Bullock, the BOE’s Bailey, and several FOMC members all due to speak at various points through the week.
WTI Crude Oil: Consolidating Below the Break as the Dollar Stays Firm
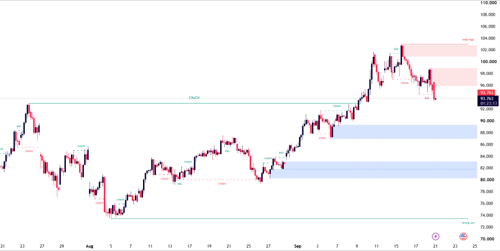
Chart: WTI Crude Oil, Weekly timeframe (TradingView, SMC)
The weekly chart shows a strong uptrend building from a low near 72 in early August, with a sequence of breaks of structure and changes of character carrying price steadily higher through the 80 to 90 region and on to a high just above 103 by mid-September. A bearish change of character off that high, followed by a break of structure back through 97, has since carried price down to its current level of 93.76, with a further break of structure just below current price adding to the near term pressure.
Overhead, the 96 to 98 zone that price recently broke below is the first resistance to reclaim, with the 103 high the major ceiling further out. Below current price, the 88 to 90 zone is the first real demand area, with the deeper 80 to 82 zone the next support if that fails to hold.
The macro backdrop remains a headwind for now. Brent crude has cooled from its recent highs, but $100-plus oil is still described as keeping bond markets on edge, and reporting this week noted that Middle East supply is holding up despite a Saudi pipeline outage, easing some of the supply-side premium that helped drive the move to 103. With the Fed seen by some as having further hikes in store for October and December, continued dollar strength is likely to stay a headwind for oil unless supply headlines turn more disruptive.
USD/CHF: A Break Higher Meets the SNB
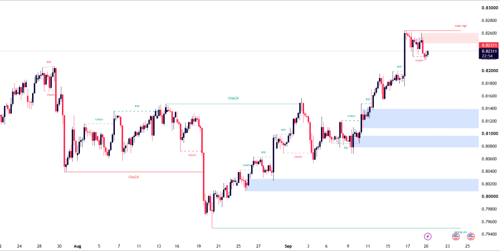
Chart: USD/CHF, Daily timeframe (TradingView, SMC)
USD/CHF’s daily chart shows a sustained recovery from a low near 0.7940 in late July, working higher through a series of breaks of structure and changes of character via the 0.804, 0.808, and 0.812 to 0.814 zones. A sharp break of structure in the middle of last week carried price up to a high near 0.8260, and a change of character off that level has since pulled the pair back to its current level of 0.8231.
Overhead, the 0.8260 high is the first level to reclaim for the uptrend to resume, with little clear structure above that on the current chart. Below current price, the 0.8120 to 0.8140 zone is the first real demand area, with the 0.8080 to 0.8100 and 0.8020 zones the deeper supports if the pullback extends.
Wednesday’s SNB decision is the defining event for the pair this week. The policy rate is forecast to hold at 0.00%, where it already sits, so with no move expected, it is the tone of the statement and the accompanying press conference that carry the real potential to move CHF. Any hint of currency intervention concerns, or commentary on franc strength, would be worth watching closely given how much ground USD/CHF has covered to the upside over the past two months.
Key Events This Week
Monday 21 September ECB and BOC Speakers
A relatively quiet start to the week on the data front, with ECB President Lagarde and BOC Governor Macklem both due to speak. FOMC member Goolsbee also speaks, with markets parsing any post-hike commentary on the pace of further tightening.
Tuesday 22 September RBA Governor Bullock and Flash PMIs Loom
RBA Governor Bullock speaks in the Asia session, a high impact event given the market’s hawkish lean toward the RBA. UK public sector borrowing data and a further ECB Lagarde appearance round out the session ahead of Wednesday’s PMI releases.
Wednesday 23 September Flash PMIs Across Europe and the UK
French, German, and UK flash manufacturing and services PMIs all land through the European morning, giving an early read on how the region’s economies are tracking into the final quarter. German services PMI is forecast to improve to 49.9 from 48.5, while UK services is expected to ease slightly to 52.0 from 52.8.
Thursday 24 September SNB Decision and Australian Jobs
The Swiss National Bank’s policy rate decision, monetary policy assessment, and press conference are the headline event, with the rate forecast to hold at 0.00%. Australian employment data, also high impact, is expected to show a 20,900 rise in jobs after last month’s 15,800 drop, with the unemployment rate seen holding at 4.5%. US unemployment claims and Canadian retail sales round out the session.
Friday 25 September BOE Governor Bailey Speaks
Bank of England Governor Bailey rounds out the week with a high impact speaking appearance, alongside the revised University of Michigan consumer sentiment and inflation expectations readings out of the US, both worth watching for any shift in how US consumers are processing the Fed’s hiking path.
Risk Warning: Trading financial instruments, particularly those involving leverage, involves a substantial degree of risk and is not appropriate for all investors. The value of your investments can rise or fall sharply, and it is possible to lose the entirety of your invested capital. Do not trade with funds you cannot afford to lose. Nothing in this site should be read or construed as constituting advice on the part of Taurex or any of its affiliates, directors, officers or employees.